ABC analysis: how to do it for products, customers and stock
Ask a buyer which product matters most to the business and they will almost always point to the best seller. Ask which product actually pays the bills and the answer changes. ABC analysis exists to take the guesswork out of that conversation: it ranks items by their weight in the result and shows, in one simple table, where attention, cash and shelf space should go.
The catch is that most guides only teach half the method. They rank by revenue, apply the 80/15/5 cut-offs and stop there. That is a fine starting point, but it can hide a low-margin product dressed up as a sales champion. Below you will find the step-by-step, a worked example from start to finish and the adjustment that actually changes purchasing decisions.
Short answer: to build an ABC analysis, list your items with each one’s value for the period (revenue, margin or consumption cost), sort them from highest to lowest, calculate each item’s share and the cumulative share, then classify: class A up to roughly 80% cumulative, class B up to 95% and class C for the rest.
What ABC analysis is and where the 80/15/5 rule comes from
ABC analysis is an application of the Pareto principle: in almost every business, a few items concentrate most of the value. In practice you will see something like 20% to 30% of products accounting for around 80% of revenue, plus a long tail of items that add up to very little.
The 80/15/5 cut-offs are a convention, not a law. Some companies use 70/20/10; others define classes by item count instead of cumulative value. What matters is picking one rule, writing it down and sticking to it, otherwise month-over-month comparisons stop meaning anything. One honest caveat: with a 15-item catalogue the curve is nearly obvious. It becomes truly valuable once you have a few hundred SKUs or customers and nobody can keep the ranking in their head anymore.
How to do an ABC analysis in 5 steps
- Choose the yardstick and the period. Revenue to understand sales, contribution margin to understand profitability, consumption value (unit cost × quantity used) for inventory. Use 12 months to smooth out seasonality, or a quarter if your mix changes quickly.
- Sort items from highest to lowest value.
- Calculate each item’s share of the period total.
- Add up the cumulative share, row by row.
- Apply the cut-offs: A up to 80% cumulative, B up to 95%, C for the rest.
In Excel or Google Sheets, with values in column C starting at row 2, the cumulative share is =SUM($C$2:C2)/SUM($C$2:$C$11) and the class is =IF(E2<=80%,“A”,IF(E2<=95%,“B”,“C”)) (type straight quotes in the spreadsheet). That works until row counts and multiple data sources start choking the file, which we cover in the post on spreadsheet limits in Excel.
ABC analysis example with real numbers
Picture a Brazilian cosmetics distributor that supplies hair salons. To keep it simple, take 10 products that brought in R$ 120,000 in revenue over the quarter:
| Product | Revenue | % of total | Cumulative % | Class |
|---|---|---|---|---|
| Shampoo 1 L | R$ 42,000 | 35.0% | 35.0% | A |
| Hair color kit | R$ 31,500 | 26.2% | 61.3% | A |
| Hair mask | R$ 18,900 | 15.8% | 77.0% | A |
| Conditioner 1 L | R$ 9,800 | 8.2% | 85.2% | B |
| Finishing oil | R$ 6,300 | 5.2% | 90.4% | B |
| Hot air brush | R$ 4,200 | 3.5% | 93.9% | B |
| Disposable gloves | R$ 2,900 | 2.4% | 96.3% | C |
| Satin cap | R$ 2,100 | 1.8% | 98.1% | C |
| Fine comb | R$ 1,400 | 1.2% | 99.2% | C |
| Hair pins (box) | R$ 900 | 0.8% | 100.0% | C |
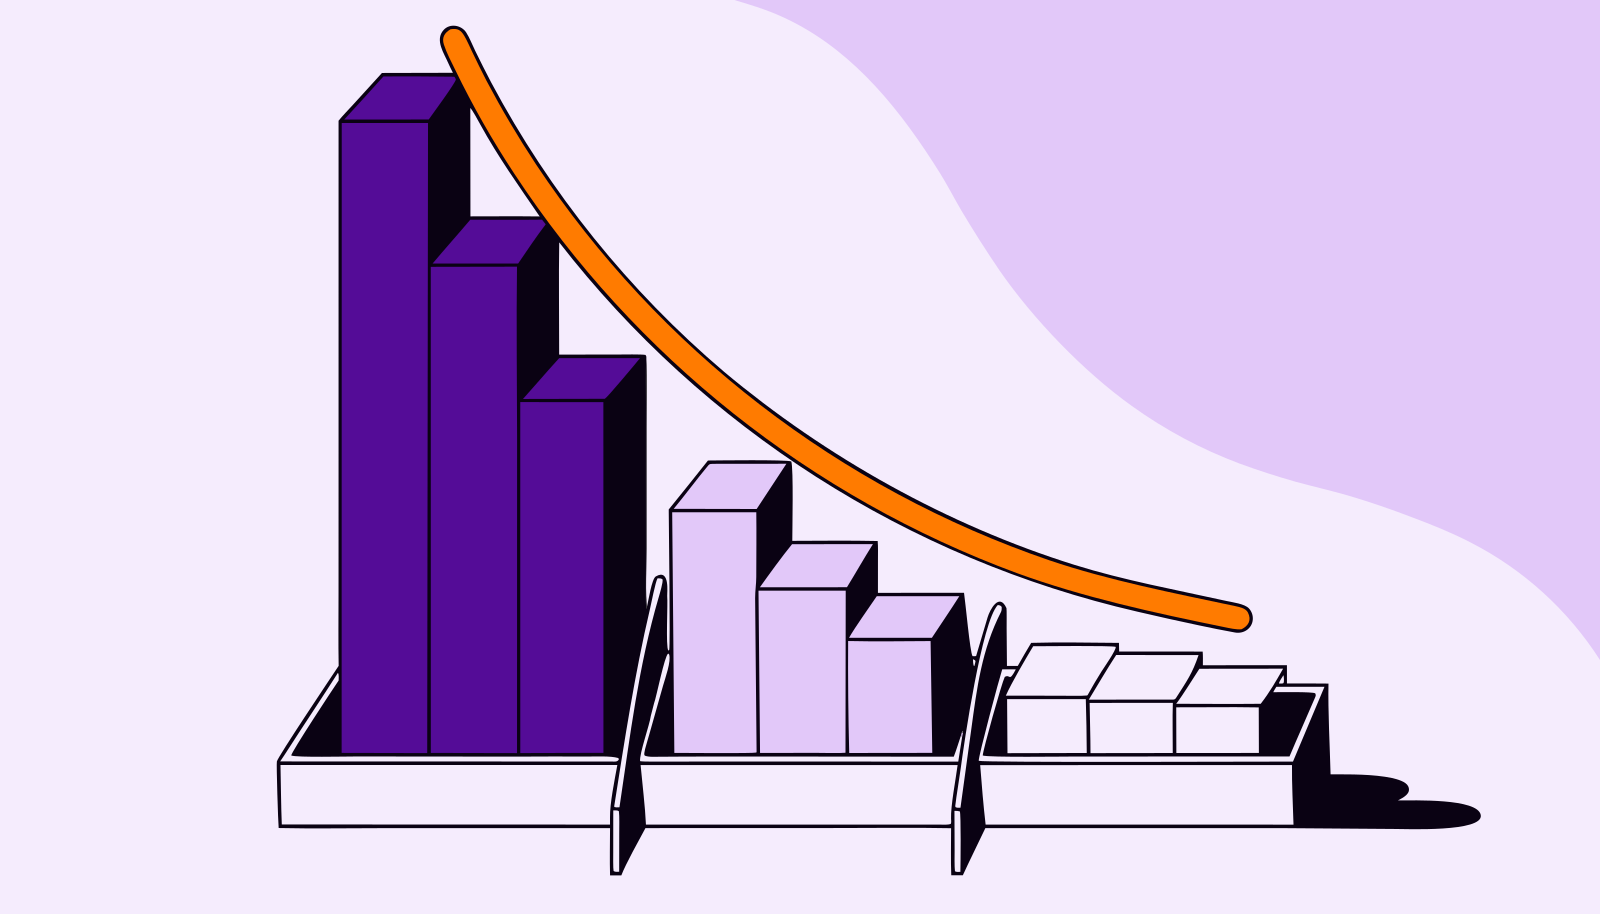
The result: 3 items (30% of the mix) are class A and add up to 77% of revenue. Another 3 make up class B, with 16.9%. The remaining 4, class C, account for 6.1%. It is the classic Pareto shape, and the chart makes it plain.
So far, the obvious reading would be: protect the shampoo, the color kit and the mask at all costs and treat everything else as secondary. That is exactly where the mistake lives.
ABC analysis by revenue or by margin?
Now add each item’s contribution margin. The 1-liter shampoo is the distributor’s door-opener: it is priced aggressively to win the salon, and its margin sits at 8%. The finishing oil, on the other hand, carries a 62% margin. Rebuild the curve using margin in currency (revenue × margin) and the quarter’s total is R$ 33,526. The order shifts:
- Hair color kit: R$ 11,025 (32.9%), stays in class A.
- Hair mask: R$ 9,072 (27.1%, 59.9% cumulative), stays in A.
- Finishing oil: R$ 3,906 (11.7%, 71.6% cumulative), climbs from B to A.
- Shampoo 1 L: R$ 3,360 (10.0%, 81.6% cumulative), drops from A to B.
That does not mean dropping the shampoo. It opens the order and pulls the rest of the basket along, so it is still strategic. It means supplier negotiations, safety stock and sales effort should not revolve around it alone. The finishing oil, which the revenue curve buried in class B, deserves visibility, promotion and zero stockouts. If margin math is still fuzzy in your company, read how to calculate contribution margin before building the curve.
The rule of thumb: the revenue curve answers “what moves”; the margin curve answers “what pays the bills”. Run both and watch the items that switch classes. That is usually where money is hiding.
ABC inventory analysis: what to do with each class
For inventory, the most useful yardstick is consumption value: unit cost times the quantity that went out during the period. The classification is there to dose control, because counting everything every week is expensive and counting everything once a year is risky. The risk is real: the Abrappe survey on retail losses in Brazil, presented in January 2026, put Brazilian retail losses at R$ 36.5 billion, or 1.51% of revenue in 2024, and tied about 70% of them to operational breakage, theft and inventory errors.
| Class | Stock counts | Safety stock | Purchasing decision |
|---|---|---|---|
| A | Cycle counts, weekly or monthly | Lean, with frequent replenishment | Weekly review with a demand forecast |
| B | Quarterly | Moderate | Reorder point, reviewed monthly |
| C | Twice a year or annually | Can be generous (cheap item) | Automatic replenishment or mix review |
One caution: class C does not mean “doesn’t matter”. The disposable gloves in the example are worth little, but without them the salon cannot work, and the customer switches suppliers over a missing R$ 20 item. That is why many companies cross ABC with a criticality rating or with demand variability.
Combining ABC and XYZ analysis
XYZ analysis ranks items by how predictable their sales are, measured by the coefficient of variation (standard deviation divided by the mean). Common cut-offs sit near 0.5 and 1.0: below 0.5 is X (stable), 0.5 to 1.0 is Y, above 1.0 is Z (erratic). Crossing both gives a nine-cell matrix. An AX item, valuable and stable, can run on lean automatic replenishment. An AZ item, valuable and unpredictable, needs a buyer’s eyes every week. A CZ item is often a candidate for make-to-order. To estimate demand in each cell, the methods in our post on demand forecasting apply directly.
ABC customer analysis: how to do it
The steps are the same, swapping products for customers: revenue (or, better, margin) per customer over the last 12 months, sorted, with cumulative share and cut-offs. In most B2B portfolios, class A holds a handful of names that deserve a dedicated account manager, their own commercial terms and close follow-up.
Two warnings. First, concentration: if a single customer exceeds a quarter of revenue, that is a risk, not just an A customer. Second, ABC looks at accumulated value and cannot see who is cooling off. An A customer who has not bought in 90 days stays A in the table until year-end. That is why it works best alongside RFM segmentation, which tracks recency and frequency. The same logic applies to ABC supplier analysis, useful for deciding where negotiation time pays off.
Common mistakes when building an ABC analysis
- A period that is too short: a month with Black Friday or Mother’s Day skews the entire ranking.
- Mixing in new launches: a two-month-old product lands in C for lack of history, not lack of potential. Keep them separate.
- Classifying once and forgetting: the mix changes; recalculate at least every quarter.
- Ignoring returns and cancellations: use net sales, or the most-returned item will look like the best seller.
Frequently asked questions
What percentages does ABC analysis use?
The most common convention is 80/15/5: class A holds the items that reach 80% of cumulative value, B runs to 95% and C takes the final 5%. Some companies use 70/20/10. Pick one rule and keep it so you can compare periods.
How do you do an ABC analysis in Excel?
Put items and values in columns, sort from highest to lowest, calculate each row’s share of the total and the cumulative share with a SUM over an expanding range. Then a nested IF formula assigns A, B or C based on the cumulative share.
What is the difference between ABC and XYZ analysis?
ABC measures an item’s value (its weight in revenue, margin or consumption). XYZ measures how predictable its demand is. Together they show not only what matters, but how hard each item is to plan.
How often should you update an ABC analysis?
For products and inventory, monthly or quarterly, always on a rolling 12-month window so you do not overreact to seasonal spikes. For customers, quarterly is usually enough, as long as a recency indicator raises the alarm earlier.
Does ABC analysis work for service businesses?
Yes. Swap products for service types, contracts or clients and use revenue or margin per hour delivered. Clinics, agencies and firms often discover that a few services carry the margin and some of the best sellers lose money once team time is counted.
The curve is easy; keeping it alive is the job
Calculating an ABC analysis takes an afternoon. Keeping it alive is the hard part, because sales live in the ERP, margin in finance’s spreadsheet, inventory in yet another system, and every month someone has to stitch it all together again. The companies that decide better are not the ones with the prettiest spreadsheet, but the ones that look at the revenue and margin curves every month and act on the items that changed class. That is the kind of question Sherlok answers: connect your sources, ask in plain language “which products dropped from class A to B by margin this quarter?” and get the analysis ready to use.
Your AI agents already know what to do in your account.
Turn them on free, no credit card.
- No credit card
- Read-only access
- Revoke it any time